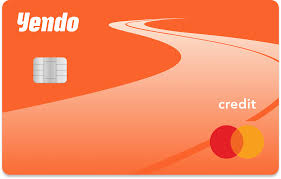
Yendo Credit Card
Facts You Need to Know
Finding a credit card when your credit history isn’t perfect can be frustrating. Traditional credit cards may offer smaller limits, require a security deposit, or simply be unavailable to applicants with limited or damaged credit histories.
That is where the Yendo Credit Card takes a rather different approach.
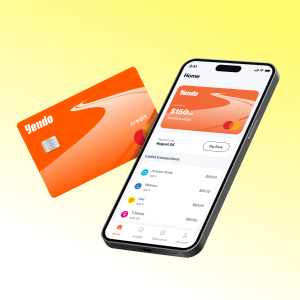
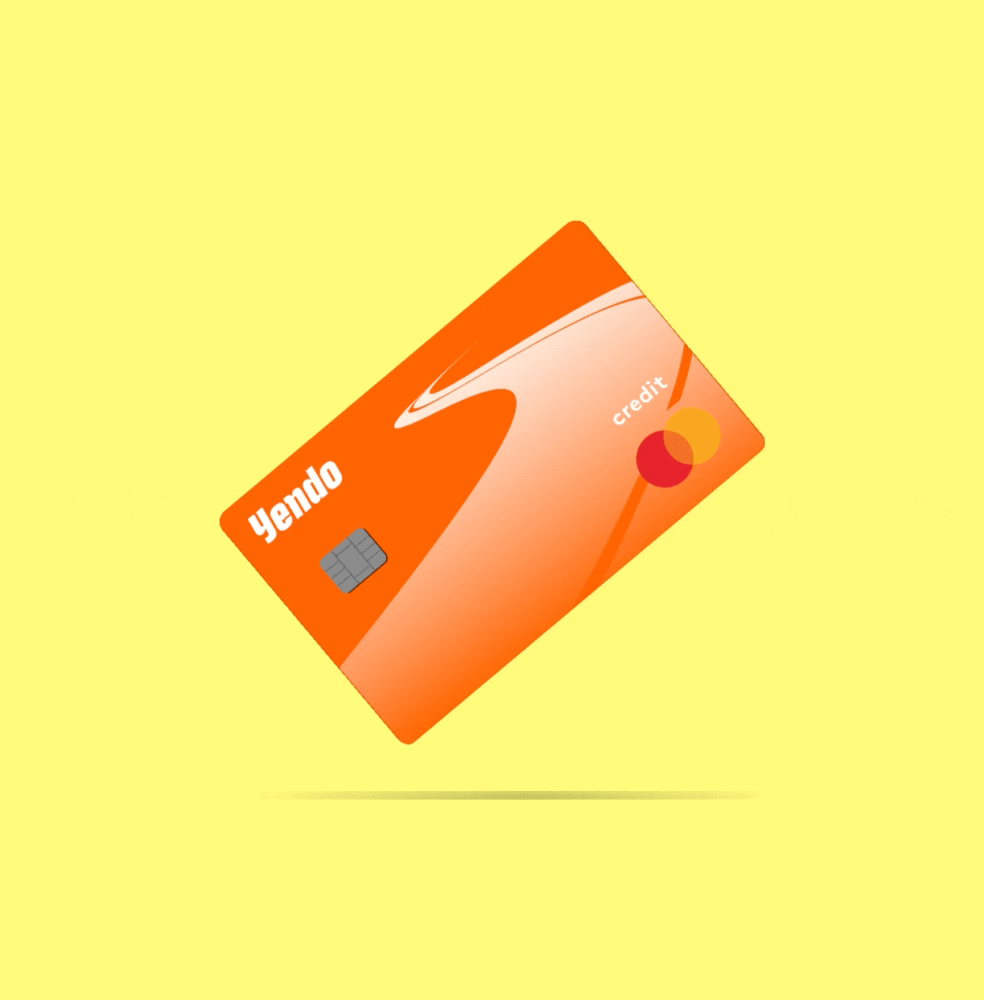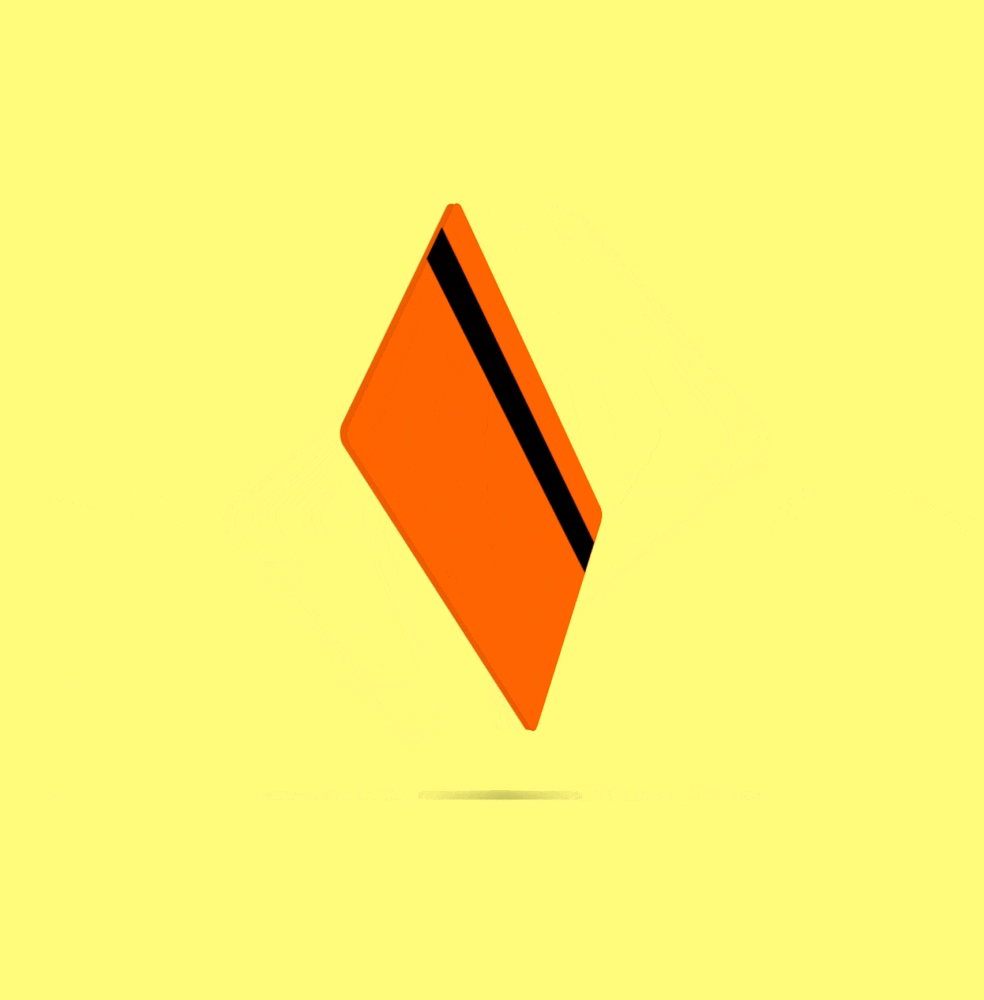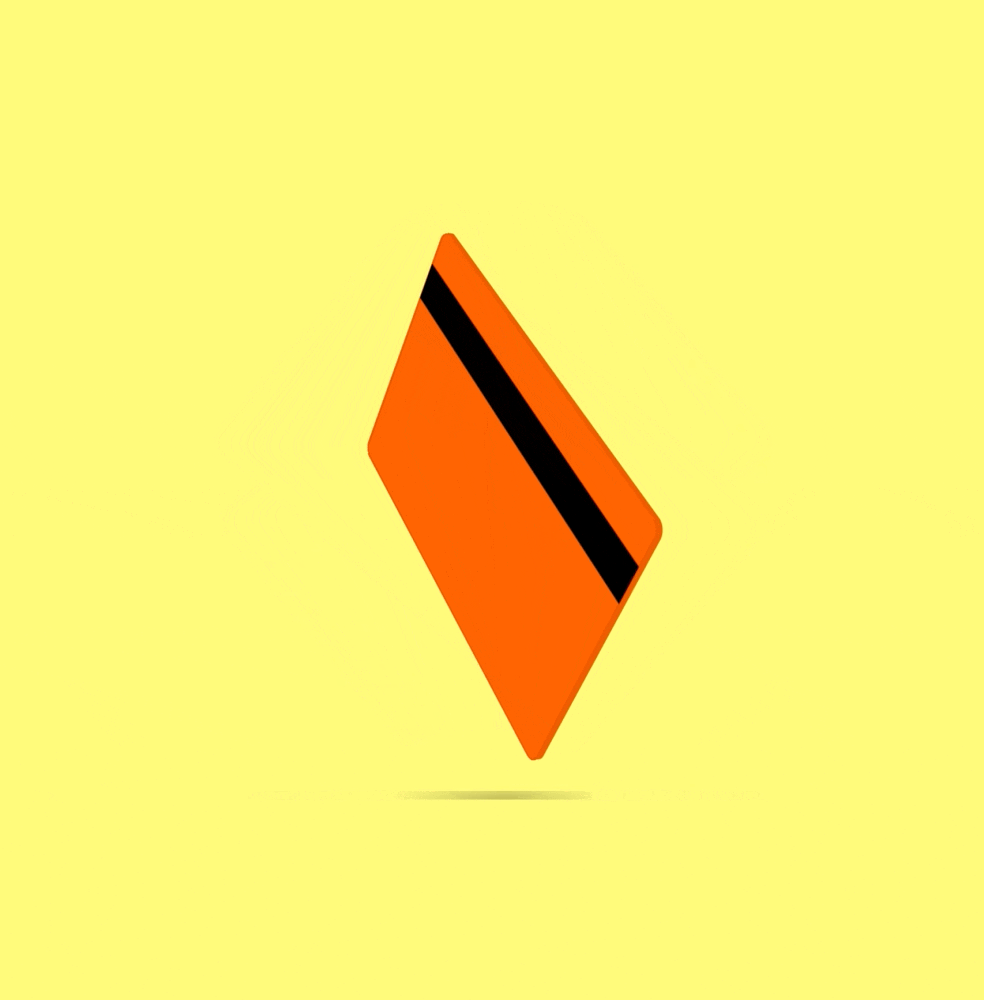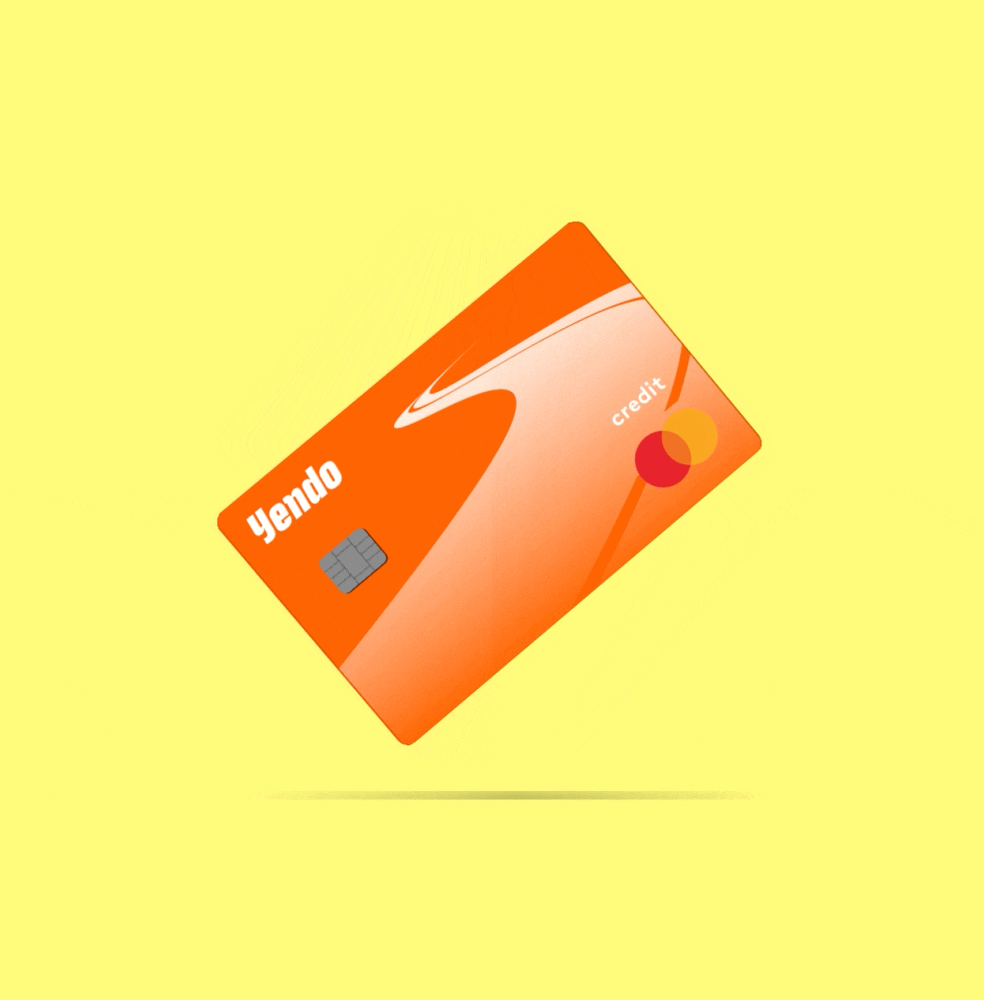
Instead of relying primarily on your credit score, Yendo uses the value of your vehicle to secure a revolving line of credit. In Yendo’s words, it is a credit card “powered by your car.” The company says applicants can access credit limits from $450 to as much as $10,000, depending on factors including the vehicle, credit history, income and ability to repay.
For someone looking to build or rebuild credit while gaining access to a potentially useful credit line, that makes Yendo an intriguing alternative.
A Credit Card With a Difference
The biggest thing that sets Yendo apart is that it isn’t simply another credit card.
When you open a Yendo account, a lien is recorded against your vehicle’s title. However, you keep possession of the car, remain responsible for its registration and insurance, and continue driving it normally. Yendo says it does not install a tracking device or starter-interrupt device.
This arrangement allows Yendo to take the value of your vehicle into consideration when determining your available credit.
That could be particularly interesting for consumers whose credit history doesn’t tell the whole story.
Yendo says that perfect credit isn’t required and that people with a thin credit file or lower credit scores may still be considered. The company evaluates the vehicle and ability to repay alongside credit history rather than relying exclusively on a conventional credit score.
No Traditional Security Deposit
Another appealing feature is that Yendo doesn’t require the cash security deposit associated with many traditional secured credit cards.
With a conventional secured card, you might have to deposit several hundred dollars before receiving a comparable credit limit. With Yendo, the vehicle provides the security instead, allowing your cash to remain in your bank account.
That doesn’t make Yendo risk-free, of course. Your vehicle is securing the account, and the lien remains in place while the account is open. But for someone who owns a vehicle and would rather not tie up cash in a security deposit, this structure could be attractive.
Up to $10,000 in Credit
Yendo advertises credit limits ranging from $450 to $10,000, with the actual amount determined individually. The company says vehicle value, make, model, mileage and condition can all play a role, along with credit history and ability to repay.
For someone who has struggled to obtain a meaningful credit limit elsewhere, that potential is worth noting.
Yendo also says it periodically reviews eligible accounts for possible credit-limit increases based on account performance. So responsible use may provide an opportunity for the credit line to grow over time.
It Can Help Build Credit
Perhaps one of the most important benefits for someone trying to improve their financial profile is credit reporting.
Yendo says it reports account activity to Experian, Equifax and TransUnion, the three major U.S. credit bureaus. With responsible use, Yendo says the card can help consumers build their credit.
That makes the card potentially more than simply a source of emergency purchasing power.
Used carefully, it could become part of a longer-term credit-building strategy: make purchases, keep balances manageable, make payments on time and allow a positive payment history to develop.
Naturally, no credit card can guarantee a particular improvement in your credit score. Individual circumstances and the way other accounts are managed also matter.
1.5% Unlimited Cash Back
There’s another pleasant surprise.
Yendo’s current Auto Card advertises unlimited 1.5% cash back on eligible purchases. The reward is provided as a statement credit when the cardholder is enrolled in autopay.
There are no rotating bonus categories to remember and no spending cap mentioned for the advertised 1.5% reward.
For someone who uses the card regularly and pays the statement balance in full, that can make the card considerably more interesting than a basic credit-building product.
Paying in Full Makes a Big Difference
Yendo currently advertises a fixed purchase APR ranging from 24.88% to 35.88%, depending on the account. The annual fee for the Auto Card is $40, and a one-time vehicle-title lien placement fee of up to $25 may also apply.
Those aren’t insignificant costs.
However, Yendo states that if you pay your statement balance in full by the due date each month, you pay no interest on purchases.
That makes responsible card management especially important.
The card should not be viewed as inexpensive borrowing simply because it offers access to credit. Carrying a balance can become costly at the advertised APRs.
There are also fees associated with cash advances, and Yendo says balance transfers, when available, carry their own terms and fees.
The Important Downside: Your Car Secures the Account
This is the biggest consideration anyone should understand before applying.
Yendo isn’t simply using your car as a way of calculating your credit limit. A lien is actually recorded against the vehicle’s title.
If you pay the account down to zero and close it, Yendo says it will release the lien within 10 days of confirming that the account has been settled, subject to circumstances such as DMV processing times.
But while the account remains open, the lien remains.
Yendo also states that if an outstanding balance isn’t repaid, it can ultimately act as a lienholder to recover the outstanding balance, following written notice and as a last resort.
So this is definitely a card that should be used responsibly. Anyone who isn’t comfortable putting their vehicle behind a credit line should consider an alternative.
Who Could Find Yendo Interesting?
Yendo could be worth investigating for someone who:
- Owns a qualifying vehicle.
- Lives in the USA
- Has less-than-perfect or limited credit.
- Wants to build or rebuild credit.
- Doesn’t want to make a traditional cash security deposit.
- Wants a potentially larger credit line than some credit-building cards provide.
- Likes the idea of unlimited 1.5% cash back on eligible purchases.
- Is confident they can make payments responsibly.
On the other hand, someone with excellent credit and access to cards offering substantially lower APRs, larger rewards or no annual fee may have plenty of other options to investigate.
The Bottom Line
Yendo is certainly an unusual credit card — and that’s what makes it interesting.
Rather than asking consumers with imperfect credit simply to accept a tiny credit limit or put cash into a security deposit, Yendo takes another approach: use the equity in your vehicle to support a revolving credit line.
The combination of potentially up to $10,000 in credit, no traditional cash deposit, reporting to all three major credit bureaus, a virtual card, possible credit-limit increases and 1.5% unlimited cash back gives Yendo some genuinely appealing features.
But the trade-off is equally important: your vehicle secures the account, and the card carries a $40 annual fee and relatively high potential APRs.
For the right consumer, particularly someone focused on establishing or rebuilding credit, Yendo may be an option worth putting on the research list. The key is to understand exactly how the card works, read the terms carefully and — wherever possible — pay the statement balance in full.
For the latest terms, eligibility requirements and application information, consumers should always check Yendo’s official website before applying.
CLICK HERE for full details. (USA ONLY – Affiliate Disclosure)
And if you’re looking for more straightforward information about credit cards, credit scores, budgeting and ways to get more value from your credit cards, there’s plenty more to explore at:
Visit wisecreditcardconsumer.com for practical information designed to help U.S. consumers make smarter decisions about their credit cards — and don’t forget to grab the site’s free 84-page guide, “How to Turn Your Credit Card Into Gold”.
This article is for informational and illustrative purposes only.
I hope you found this article useful & helpful.
To your continued success
Steve Searle